Canada lags peer countries in venture philanthropy support for innovative startups

Canada lags the United Kingdom and United States in venture philanthropic support for startups, but Kyle Briggs and his colleagues aim to galvanize more innovation-focused philanthropy in this country.
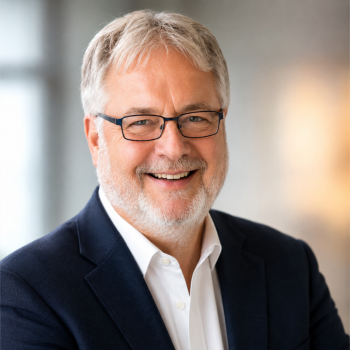
 “We’re at least 20 years behind the U.K. on the venture philanthropy piece, at least as far as emerging technology commercialization goes,” said Briggs (photo at right), startup founder, entrepreneur in residence at the University of Ottawa, and owner of the CanInnovate website
“In the U.S., venture philanthropy is well-established,” he said in an interview with Research Money. “In Canada, venture philanthropy is relatively new.”
“I would say philanthropic capital is generally underutilized in Canada, specifically as a support mechanism for innovation and prosperity through innovation. That has been very effective in other jurisdictions,” Briggs said.
There are only a handful of Canadian universities engaged in venture philanthropy, such as the University of Calgary (UCalgary) which operates its UCeed fund through Innovate Calgary, Briggs said.
UCeed is the largest philanthropically driven, university-based investment fund of its kind in Canada. It consists of early-stage investment funds, backed by philanthropic support, aimed at accelerating early-stage startup companies to advance problem-solving research, create jobs and fuel the economy.
In comparison with the handful of Canadian universities engaged in venture philanthropy, the U.K.’s UK12S fund has operated for about 20 years, Briggs said. The fund, which manages £150 million in assets, makes dilutive investments the same way an angel or VC fund would, but whenever there's return on that investment, instead of sharing it among limited partners, it's reinvested. “So it gets recycled into the fund and supports the next generation.”
The UK12S invests in six key investment areas: defence & security; engineering biology; fusion; knowledge assets; partner innovation; and space.
About 80 percent of the companies the UK12S invests in, which are all university spinouts with emerging technologies, attribute their existence to that first cheque from UK12S, Briggs said. “They either wouldn't have gotten off the ground in the first place or would have had to shut down because they couldn't access capital, except that UKI2S took the risk on them.”
In the U.S., one example of a philanthropy-backed fund is the T1D Fund, a scaled venture impact fund accelerating treatments, prevention and cures for the approximately 9 million people living with type 1 diabetes. The fund manages more than US$200 million in assets.
In Canada, almost every major hospital operates with a parallel public foundation that serves as its official philanthropy and fundraising arm. These distinct, registered charitable entities manage endowments, accept donations and organize campaigns to purchase advanced medical equipment, fund clinical research, and upgrade healthcare facilities.
For example, the SickKids Foundation is the philanthropic and fundraising arm of the Hospital for Sick Children in Toronto. The foundation – the largest charitable funder of child health research in Canada – raises funds for pediatric health care, research and learning.
“There's certainly lots of philanthropic capital that's aimed in the early stages in the health space in particular, but it's typically not venture philanthropy in the venture sense, which is to say it's more often grants than investments,” Briggs noted.
“What distinguishes venture philanthropy from grants is that there is that dilutive investment piece. There is a return in principle but that it gets recycled rather than becoming profit for somebody else.”
However, Canadian philanthropic organizations and charities generally do not directly hand out seed capital or investment funds to startups.
For example, the Upside Foundation of Canada, a registered charity, enables high-growth early-stage companies to pledge a portion of their equity (stock options or warrants) to Canadian charities. When the startup is acquired or goes public, the equity is converted to cash and donated to charity. It allows founders to build philanthropy into their business model before they have liquid cash.
Canada lacks philanthropic venture funding for the “Valley of Death”
Briggs said what Canada lacks is philanthropic venture funding that directly supports startups through the “Valley of Death,” a period where startups are pre-revenue and are still doing R&D to develop their technologies.
“They’re no longer eligible for academic grants anymore and Canadian for-profit VC won't touch them,” because it’s too financially risky, he said.
As for securing federal or provincial grants, most of these public sector innovation funds either require matching funds from the company or that the company spend money and get reimbursed later, he added.
“And these pre-revenue companies don't have capital to match. They don't have capital to spend, so they can't make use of the public funds very effectively,” he said.
Briggs said his analysis based on a dataset from PitchBook, of about 9,000 actual university spinouts, revealed that the private sector isn’t involved in closing this Valley of Death investment gap because of the time it takes to get a return on investment.
These startups take time to become established and grow, so over a 20-year time horizon the medium return on investment is a bit below the public markets, he said. It’s only after about 40 years that the medium return is greater than the public markets.
“It’s not a rational choice for a for-profit investor to lock up their capital for 20-plus years, only then to find out whether they beat the public markets or took a haircut on the entire thing,” Briggs said.
If a company is able to survive and get to the scaling stage, then there is venture capital available in Canada and much more so in the U.S.
“It’s something that makes sense from a for-profit investor point of view. So there's no market failure at that stage,” Briggs said.
But for very early-stage companies, private sector capital doesn’t make sense and public sector funding is structurally inefficient at that particular stage, he said.
Also, Briggs noted that the amount of capital that early-stage companies need to survive the Valley of Death is relatively small – typically a few tens of thousands to a few hundred thousand dollars compared with a scaling company that might require millions or tens of millions of dollars.
“So venture philanthropy really finds its sweet spot, both in terms of the size of checks relative to the amount of capital that you can assemble into these funds, but also where it is most impactful,” he said. “And the sweet spot really is that emerging stage, that pre-revenue stage where these companies would struggle to find capital otherwise.”
Venture philanthropy offers patient capital over long time horizons
Business capital needs a return within a defined window, Lisa Lalande, CEO of Century Initiative, said in a LinkedIn post.
In comparison, “Philanthropy can hold a twenty-year horizon, fund research nobody has a mandate for, convene people who will not sit in a government room, and pay to find out whether an idea works before a country bets on it,” she said.
“That is not charity. It is infrastructure for thinking long,” Lalande said.
Canada is undertaking our its ambitious build in decades: major projects, critical minerals, trade corridors and defence, she noted. “But every [investment] vehicle we have created is designed around what can earn a financial return or justify public expenditure.”
Government and business will continue to move on these priorities, she said. “But neither is designed to fund every experiment, relationship or line of inquiry the work will require. Philanthropy can operate alongside them, taking different risks, working on a longer horizon and supporting work that falls between institutional mandates.”
There are dozens of government-supported innovation programs for businesses, offered amid constant complaints that Canada’s innovation ecosystem is too-risk adverse and Canadian investors aren’t taking enough risks.
But federal innovation programming as currently constructed is ineffective because those funds can’t be accessed by early-stage startups with no revenue or ability to match funding, Briggs said.
When early-stage, pre-revenue startups can’t secure sufficient capital, not enough of these companies survive to get to the scaling stage where for-profit VC firms become involved in investment. “Which means that it's a pretty shallow pool that actually gets there. They're getting filtered out along the way,” Briggs said.
“So it's sort of a chicken-and-egg situation where risk aversion leads to a shallow pool [of scaling companies], which creates poor returns [on investment], which justifies risk aversion. So we've been stuck in this loop,” he said.
Any sector that has a long valley of death in commercializing research could benefit from venture philanthropy, he said.
Software companies don’t require a lot of capital to get off the ground, so they can be financially bootstrapped. However, deep tech companies commercializing research, such as firms building hardware, often have a long incubation period and could benefit from venture philanthropy to survive the Valley of Death.
“At the end of the day, it's really just a question of incentives and that specific section of the innovation pipeline not being appropriately supported by either side individually. So this is where the blended finance mechanism of venture philanthropy has been effective,” Briggs said. said.
A blended finance mechanism is a mix of public-private funds, put into a dedicated nonprofit organization that can manage those funds on the time scale that university startups need – on the order of nine years or longer. “You need an institution that can operate on those kinds of time scales,” he said.
To create that institution, Briggs and collaborators David Durand and Rami Alhamad established the SAIL Fund, a venture philanthropy blended finance mechanism where both public and private philanthropic contributions make dilutive investments in companies commercializing the results of publicly funded research in Canada.
For example, Canadian sectors such as quantum, agri-food, health, biotech, life sciences and defence overlap with current national priorities and are sectors where venture philanthropy can be effective, Briggs said. “So these are the areas that we’re constructing this to go after, initially.”
The SAIL Fund is currently under construction, looking for funds and in talks with the federal government about funding the public portion of the venture philanthropy initiative.
“This is an attempt to harmonize the approach and recognize that in this specific niche [of very early-stage, pre-revenue startups], it is genuinely a combined approach that is needed in order to overcome the challenges here,” Briggs said.
But whereas a few universities are doing venture philanthropy on a local scale, the SAIL Fund “is intended to do this more broadly at a national level across the country and to start tapping into the underutilized sources of philanthropic capital for supporting prosperity through innovation,” he said.
“The intention really is to be able to finally connect the world-class outputs of Canadian publicly funded research to downstream socioeconomic impact,” he added.
“And as part of that, create the support for the very early stage, the Valley of Death basically, that will enable intellectual property to stay in Canada long enough to create value domestically that will enable founders to stay and create value domestically.”
Ottawa should establish a national, not-for-profit venture philanthropic fund
In a pre-budget submission for this fall’s federal 2026 budget, the SAIL Fund team recommends that the government provide $42.5 million over five years to establish a national, not-for-profit venture philanthropic fund to invest in pre-revenue startups creating socioeconomic value from publicly-funded research.
These funds will be matched at least 1:1 by private sector contributions, for a total funding envelope of at least $85 million.
Over 15 years, a $42.5-million public commitment could anchor more than 800 startups in Canada, “while unlocking untapped sources of philanthropic capital for innovation,” SAIL Fund’s submission says.
The SAIL Fund would invest in in three phases, inspired by internationally successful models. These models assist pre-revenue startups in developing an export-ready IP strategy and a path to market, creating de-risked, investment-, export-, and procurement-ready Canadian companies.
SAIL Fund’s submission points out that Canada failed to retain the intellectual property on the algorithms used to train modern AI. Also, semaglutide was invented in Canada and lost before its value was clear. Canada discovered insulin, but is completely import-dependent.
Canada ranks last among peer countries in university-managed venture capital, according to the submission.
The mean time to a startup receiving its first angel cheque is three years And $0.141 billion (or $141 million) in missing pre-seed and seed-stage funding compounds to $66 billion in lost economic value, according to the National Angel Capital Organization.
“Taxpayer-funded research and entrepreneurial talent generate economic activity in other jurisdictions not because that is the preferred option, but because it is the only option,” SAIL Fund’s submission says.
Over more than 18 months, the SAIL Fund team developed the Simple Agreement for Innovation Licensing (SAIL), a unique pan-Canadian deal flow network that includes university technology transfer offices, Lab To Market national networks, accelerators, federal and provincial funders, the Canadian Armed Forces, veteran interest groups, angel investor networks, family offices, not-for-profit organizations and industry groups.
As for the government mandating Canadian pension funds to invest more in Canadian companies, Briggs pointed out that these pension funds have mandates to target risk-adjusted funds that makes sense for those funds.
“If those [companies] aren't to be found in Canada as a result of us leaking IT and talent in the early stages, then the outcome is not all that surprising that this money would be going to other jurisdictions,” he said.
“So I think rather than mandating that more investment happened domestically, the task really is to do the work to make sure that it makes sense within the existing mandate to invest domestically.”
“You need the incentives to be competitive so that experienced founders and operators want to build in Canada because they're rewarded for it when they succeed,” Briggs said.
“You need to build the supports that support each part of the pipeline that leads to that outcome. And you need to do it in a way that's context-appropriate. And that really is the key for that pre-revenue stage.
“This is where venture philanthropy is, from what I have seen in my research, the context-appropriate mechanism for that particular problem.”
Moreover, it is in early-stage companies where a lot of the IT and talent leakage occurs, Briggs said. “And this is where, for a very relatively small amount of money, we could really increase the depth of the pool of investable opportunities in Canada to the point that it makes sense for that for-profit money to come in.”
As the old expression goes, “for want of a nail, the kingdom was lost,” he said. “I think that applies to a lot of research projects where a few tens of thousands of dollars would have been enough, but because they couldn't get it, they moved to the U.S. and did it there instead. And that's a tragedy.”
R$
| Organizations: | |
| People: | |
| Topics: |
Events For Leaders in
Science, Tech, Innovation, and Policy
Discuss and learn from those in the know at our virtual and in-person events.
See Upcoming Events
You have 0 free articles remaining.
Don't miss out - start your free trial today.
Start your FREE trial Already a member? Log in
By using this website, you agree to our use of cookies. We use cookies to provide you with a great experience and to help our website run effectively in accordance with our Privacy Policy and Terms of Service.